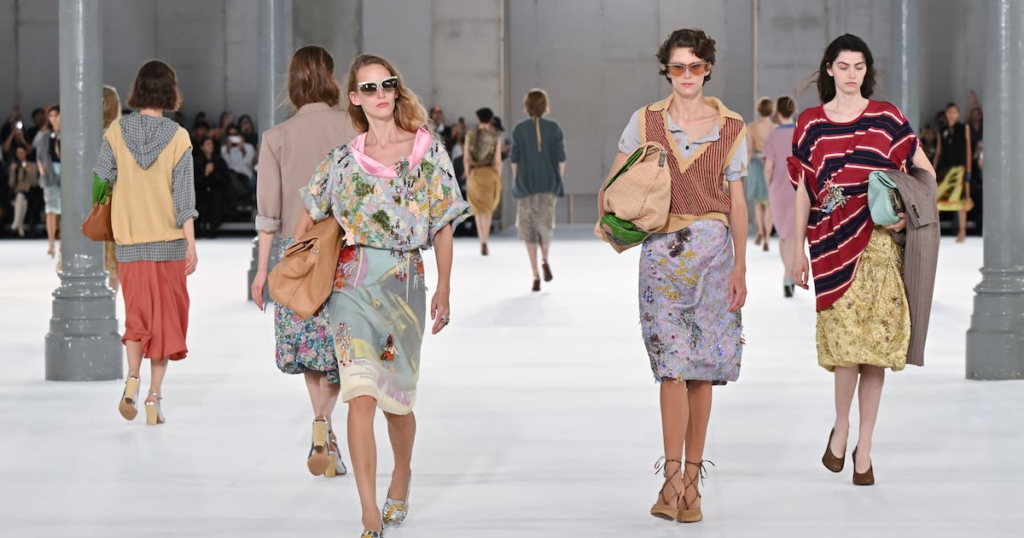

Customer engagement strengthened as the company continued to invest in brand building, physical retail, owned labels and partnerships.
Net sales rose 20 per cent year on year to $356.0 million in the third quarter ended September 30, 2026, while gross profit increased 19 per cent to $191.8 million.
US’ Revolve Group’s third-quarter net sales rose 20 per cent year on year to $356 million, driven by double-digit growth across its REVOLVE and FWRD segments and domestic and international markets.
However, net income fell 27 per cent to $15.5 million amid higher operating and marketing expenses.
The company raised the lower end of its FY26 gross-margin outlook to 53.9 per cent from 53.5 per cent.
Gross margin declined 75 basis points to 53.9 per cent. Net income fell 27 per cent to $15.5 million and income from operations decreased to $19.0 million from $21.0 million a year earlier, while adjusted earnings before interest, tax, depreciation and amortisation (EBITDA) declined 7 per cent to $23.5 million. Diluted earnings per share (EPS) were $0.20, compared with $0.29 in the prior-year quarter, Revolve said in a press release.
“We delivered a strong third quarter, highlighted by net sales growth of 20 per cent or more across our segments, REVOLVE and FWRD, and in domestic and international markets,” said Mike Karanikolas, co-founder and co-CEO, Revolve Group.
“Supporting our top-line momentum was 18 per cent growth in active customers year-over-year, our fourth consecutive quarter of growth acceleration,” added Karanikolas.
“Our strong top line growth and customer engagement metrics are a reflection of our brand strength and a result of our investments in brand building, physical retail expansion and key partnerships,” said Michael Mente, co-founder and co-CEO, Revolve Group.
REVOLVE and FWRD post double-digit sales growth
The REVOLVE segment generated net sales of $306.8 million, up 20 per cent year on year, while FWRD sales also rose 20 per cent to $49.2 million. US net sales increased 20 per cent to $277.4 million, and international sales climbed 22 per cent to $78.6 million.
Trailing 12-month active customers increased 18 per cent to 3.2 million, the company’s fastest growth rate in three and a half years. Total orders placed grew 19 per cent to 2.7 million, while average order value declined 5 per cent to $292. A lower product return rate also supported sales growth.
Margin moderates as growth investments increase
Fulfilment costs rose to $12.2 million, or 3.4 per cent of net sales, from $9.8 million, or 3.3 per cent, a year earlier. Selling and distribution expenses increased to $63.5 million, or 17.8 per cent of sales, as higher shipping rates outweighed the benefit from lower returns.
Marketing expenditure increased to $50.8 million, or 14.3 per cent of sales, from $40.4 million, reflecting higher performance and brand-marketing investment, including support for the REVOLVE Los Angeles owned label. General and administrative expenses rose to $46.2 million, while other income declined to $2.0 million from $7.3 million, as the prior-year quarter benefited from a $4.5 million insurance recovery.
Operating cash flow was negative $24.3 million, compared with positive $11.8 million a year earlier, while free cash flow was negative $27.0 million versus positive $6.6 million, primarily due to unfavourable working-capital changes. Cash and cash equivalents stood at $284.6 million at September 30, and the company remained debt-free. Inventory increased 23 per cent year on year to $293.3 million.
Revolve lifts FY26 gross-margin outlook
For fiscal 2026 (FY26), Revolve lifted its gross-margin outlook to 53.9-54.0 per cent from 53.5-54.0 per cent previously. It now expects fulfilment expenses to equal 3.3 per cent of net sales, selling and distribution expenses to account for 17.5 per cent, marketing expenses for 15.9 per cent and general and administrative expenses to reach $178.0 million. The company expects an effective tax rate of 25-26 per cent.
For the fourth quarter, Revolve forecast gross margin of 52.3-52.8 per cent, fulfilment costs of 3.3 per cent of net sales, selling and distribution costs of 17.6 per cent, marketing costs of 16.9 per cent and general and administrative expenses of $46.1 million.
The outlook considers potential consumer-spending and cost pressures from geopolitical uncertainty, tariffs, inflation, supply-chain disruption and currency volatility, and assumes no additional International Emergency Economic Powers Act tariff refunds.
Fibre2Fashion News Desk (CG)